The data says the story isn't over.
Six articles in the French financial press in recent months. Les Echos, Agefi, Option Finance, Scala Patrimoine, Cleerly, Club Patrimoine, all circling the same subject: the losses accumulated in Stellantis-linked structured products, and the role the decrement mechanism played in amplifying them.
The pattern the press describes is now well understood: the decrement kept applying after Stellantis cut and then eliminated its dividend in 2026, creating a scissor effect, that mechanically accelerated losses. Some products are now showing mark-to-market losses exceeding 99%. That's not a rounding error.
The numbers, on the surface, look contained. Decrement indices represent roughly 26% of structured product AUM; single stock exposure sits at around 5% of total market. But aggregate figures are comfortable things to hide behind. Within that 5%, the stress is anything but uniform.
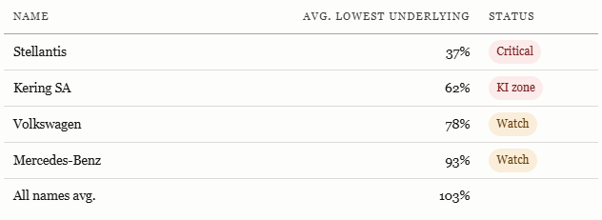 ~
Source: SPI, part of WSD. Live French products as of 27 May 2026
Stellantis is a known quantity. Kering is the new concern: at 62%, it has crossed into genuine KI barrier territory, the same zone Stellantis occupied before the press started writing about it. Luxury has had a difficult cycle: the Chinese consumer has stepped back, and the Iran conflict has dealt a further blow, with Iranian strikes on Dubai's Palm Jumeirah and the Gulf's reputation as a stable luxury destination taking direct hits. Kering has been among the hardest hit: Gucci has struggled to regain momentum, earnings have been revised down repeatedly, and the dividend that once made it a compelling decrement underlying now looks less certain. Like Stellantis, it was popular in decrement structures precisely because it was well-known, liquid, and had a healthy dividend history. The same logic that made it attractive is now working against it.
Volkswagen and Mercedes sit further back, but European autos as a sector are not giving anyone much comfort. The Stellantis press coverage consistently highlighted the "worst of" basket problem, one name pulling down the whole structure. Anyone with basket exposure across European autos should be paying attention to the correlation risk building here.
The aggregate reads 103%. That number will not make the next Les Echos headline. The names beneath it might.