It's not only on autocallable ETFs. On structured notes, defined volatility is quietly becoming one of the more consequential mechanical shifts in the US market and the growth curve backs that up.
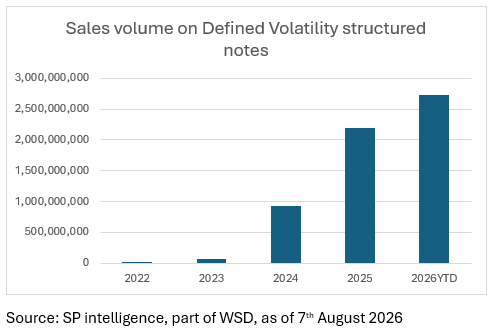
2026 YTD volume, with roughly five months still left on the clock, has already surpassed the whole of 2025. On an annualised basis that's well north of 100% YoY growth, and even taken at face value, YTD alone represents +24% over full-year 2025. This isn't a rounding blip; defined vol has gone from a $42.7mn curiosity in 2022 to a multi-billion-dollar mechanism in four years.
The 40% target has pulled away from the pack
Break the cumulative $5.94bn down by target volatility level and the picture sharpens. but the downside style isn't uniform across tiers and that's the part worth sitting with. This is where it gets more interesting than "defined vol is growing." The preferred downside mechanism actually flips depending on the target level:
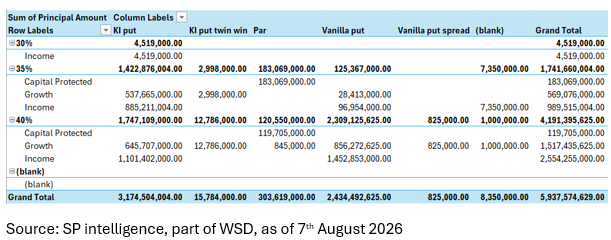
The 40% target has become the default, not just the preference. 30% is barely a rounding error at this point, $4.5m, all of it Income, and looking more like an early experiment than a live strategy.
At 40%, vanilla put narrowly leads. At 35%, KI put dominates by a wide margin. If defined vol were simply a coupon lever applied uniformly to whatever wrapper was already popular, you'd expect the downside style mix to look roughly the same across both tiers. It doesn't. That suggests desks are pairing specific vol targets with specific downside structures deliberately likely because the vol-suppression effect changes how a KI put versus a vanilla put actually prices at each target level, not because of investor preference alone.
And it's overwhelmingly an Income story
This is the point that ties the whole piece together: nearly 60 cents of every defined-vol dollar sold since 2022 has been sold as Income — and, as noted, concentrated on 5-year autocallables. Within the 40% tier specifically, Income runs even higher at 60.9%. Capital protected paper barely registers at 5.1% overall, which tells you defined vol isn't really being marketed as a risk-dampening feature for cautious investors. It's being used to manufacture better coupons on income paper that already carries capital-at-risk.