Canadian Structured Products Issuance Reaches CAD 7,460.5Mn (+19.0% YoY) as Notes Extend Their Lead Over Market-Linked GICs.
Key Highlights
- Wrapper Mix: notes issuance of CAD 6,333.2m in September (+39.5% YoY) against a 34.8% fall in market-linked GICs to CAD 1,127.3m lifts notes to 75.5% of YTD issuance, confirming a decisive rotation away from GIC wrappers.
- Product Mix: Income leads with CAD 30,821.6m (42.8% of YTD issuance), ahead of Capital protected (35.9%) and Growth (21.3%), with the contraction in GIC volume weighing on the capital protected share.
- Payoff Structures: barrier phoenix accounts for CAD 29,430.9m (41.4% of allocable YTD volume), followed by barrier digital plus (18.9%) and capped protected participation (18.7%), highlighting concentration in barrier-driven, income-oriented payoffs.
- Underlying Trends: adjusted return indices underpin CAD 42.7bn of YTD issuance (+39.2% YoY), with percentage synthetic dividend indices up 271.8% to CAD 7.2bn, reinforcing the central role of adjusted return index design.
- Asset Allocation: Equity (indices) represents 81.5% of YTD volume and Equity (shares) 11.3%, with interest rates at 4.6%, confirming the overwhelming dominance of equity exposure.
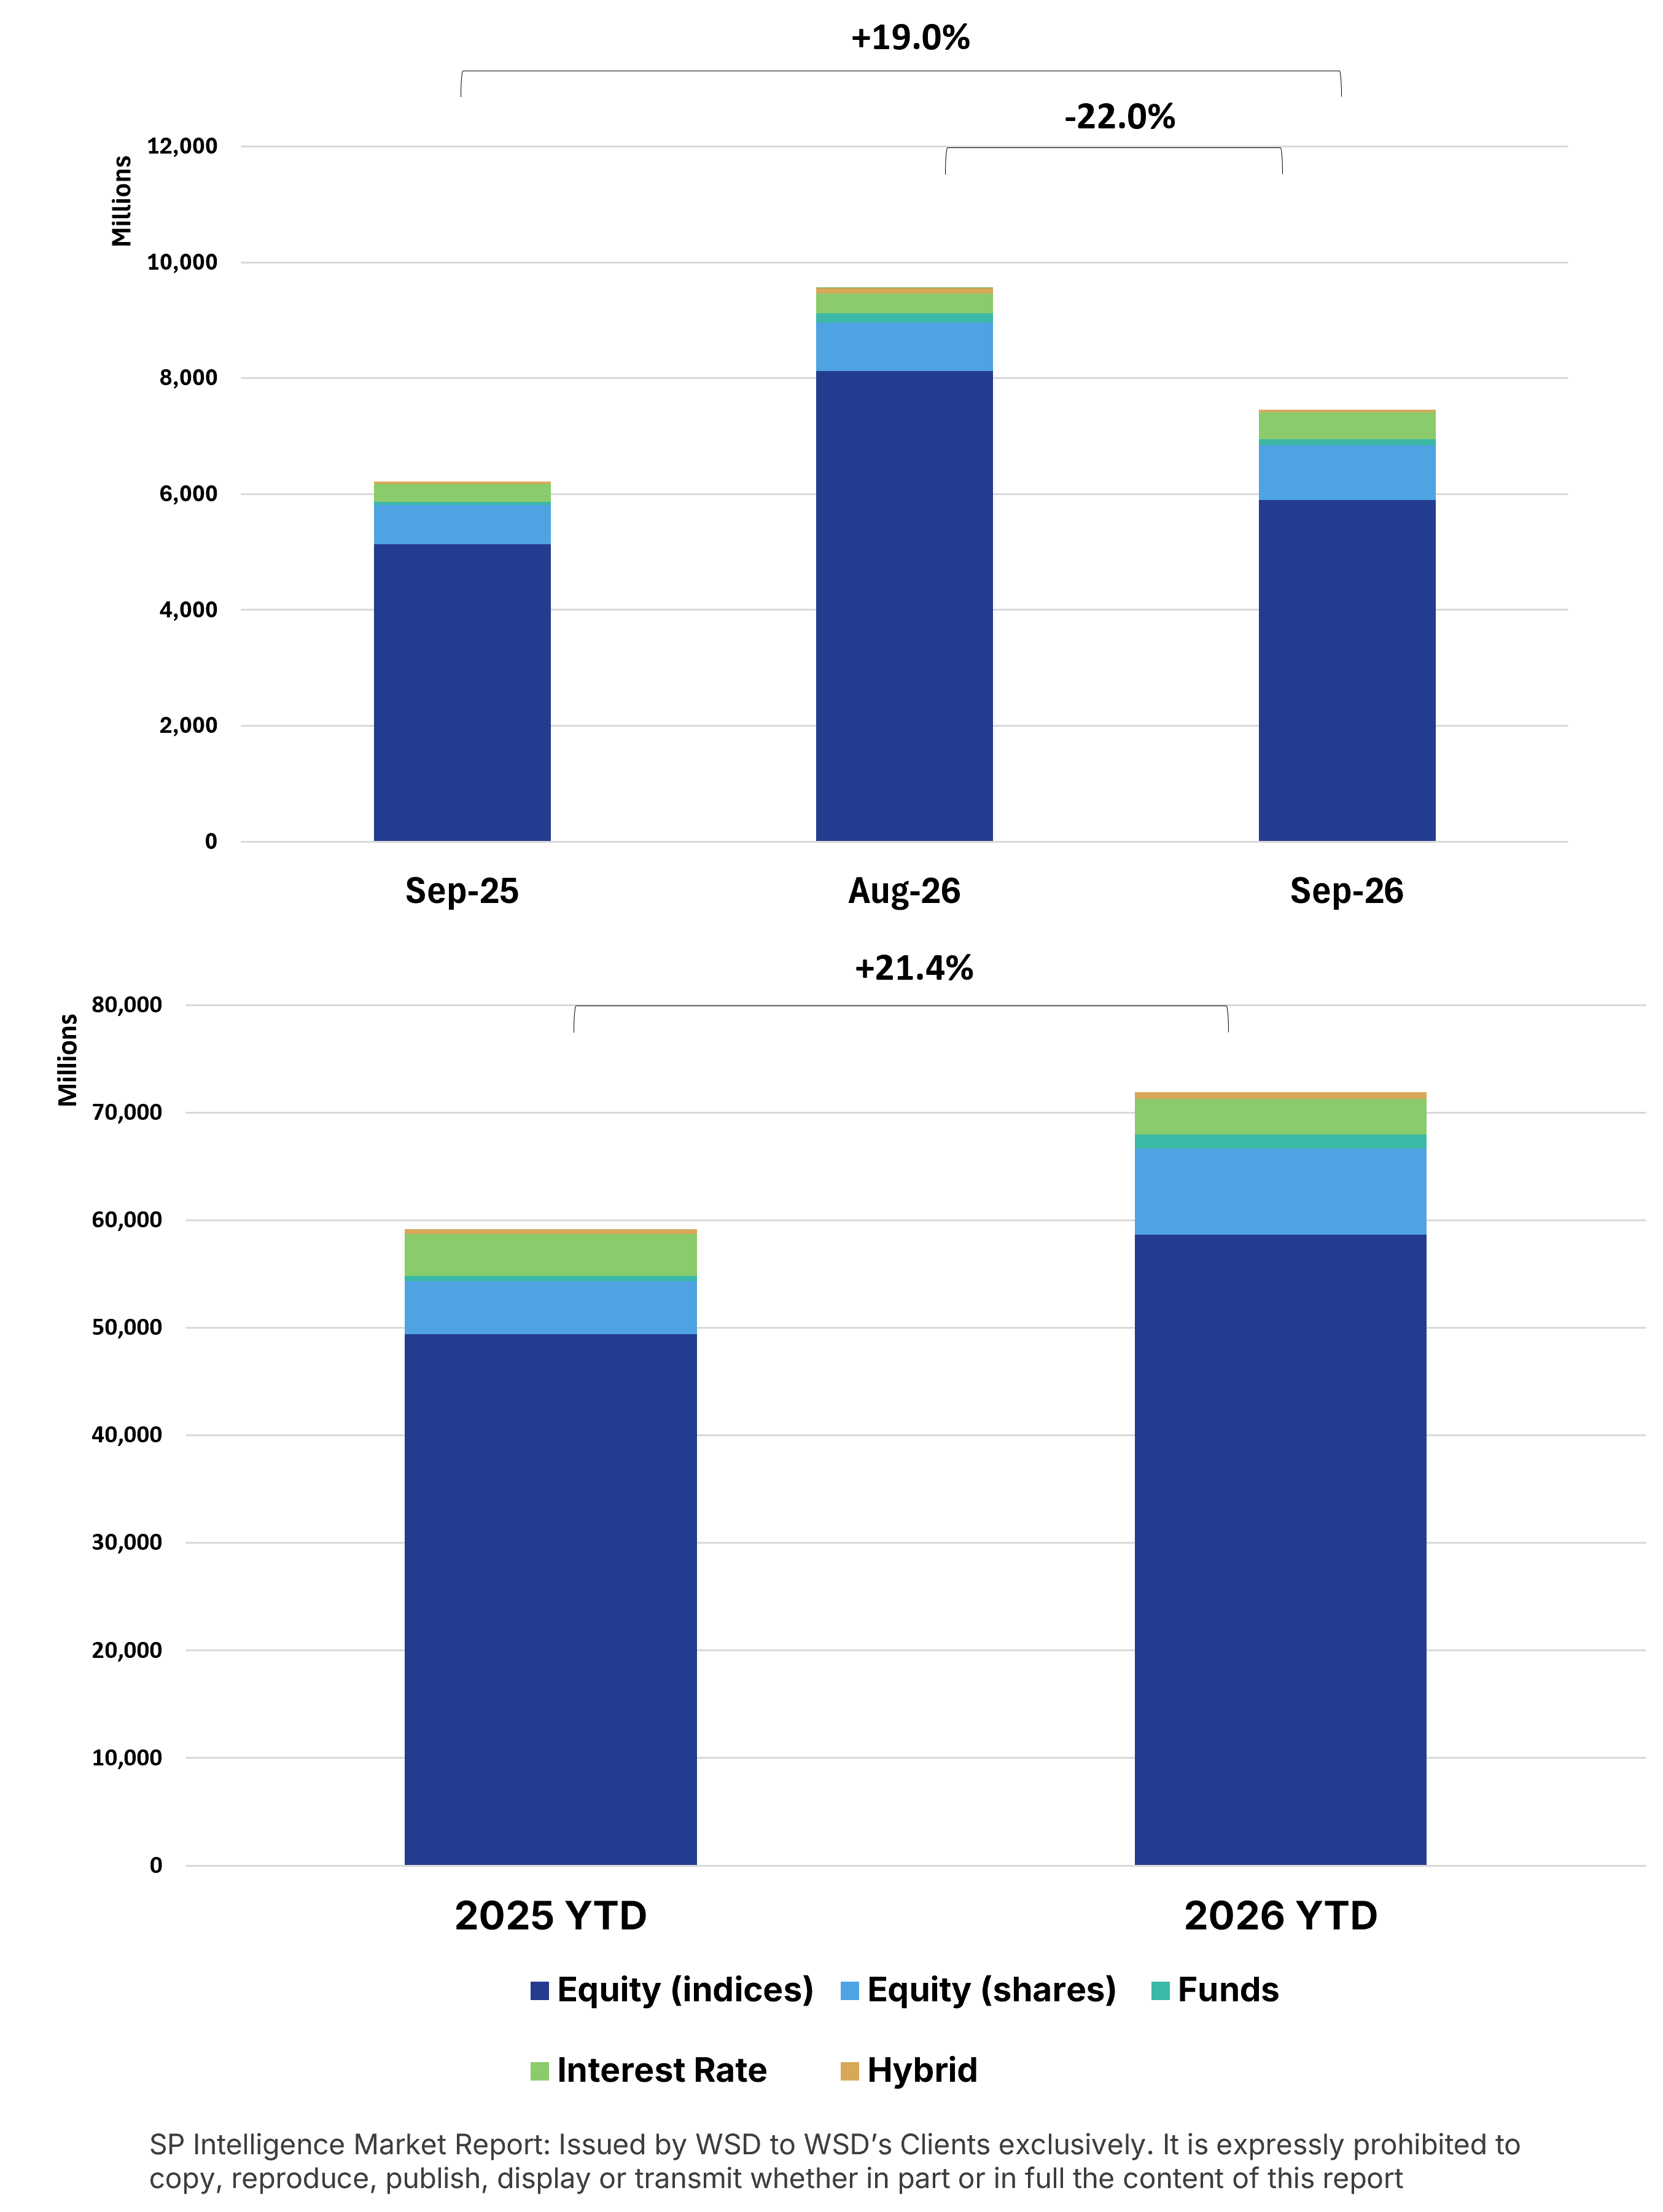
Market Overview
September 2026 confirms the sustained momentum of the Canadian structured products market, with issuance of CAD 7,460.5m, up 19.0% year on year. Q3 2026 volume reaches CAD 24,616.9m (+17.5%), and year to date issuance stands at CAD 72,004.0m, up 21.4%. The wrapper split continues to widen in favour of notes, which have grown 48.2% year to date to CAD 54,364.6m while market-linked GIC volume has contracted 22.0% to CAD 17,639.3m, leaving notes with 75.5% of issuance. Principal At Risk Notes dominate at 64.2% of year to date volume, ahead of GICs at 24.5% and Principal Protected Notes at 11.3%. By product type, Income structures lead with 42.8%, ahead of Capital protected at 35.9% and Growth at 21.3%, an ordering that follows directly from the wrapper mix. Payoff construction remains concentrated, with barrier phoenix structures accounting for 41.4% of allocable volume and barrier digital plus (18.9%) now ahead of capped protected participation (18.7%). On the asset side, Equity (indices) accounts for 81.5% of year to date volume, while adjusted return indices underpin CAD 42.7bn, up 39.2% year on year, although growth slowed to 27.2% in September. Overall, September reflects a growing, increasingly at-risk market, combining double-digit issuance growth, a decisive rotation from GICs into notes, and continued dominance of equity index-linked, barrier-driven structures.
Methodology & Notes
This report is based on SPi's proprietary database of structured products distributed in Canada. Figures reflect best-effort estimates based on available market data at the time of publication.
Disclaimers
Data Disclaimer (Best Effort / Completeness)
The information presented in this report is based on data collected from a variety of public and proprietary sources. While reasonable care has been taken to ensure accuracy, the data may be incomplete, subject to revisions, or may not capture the entirety of the market. SPi makes no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information.General Disclaimer
This document is provided for informational purposes only and does not constitute investment advice, an offer, or a recommendation to buy or sell any financial instrument or to adopt any investment strategy. The views expressed are those of SPi at the date of publication and are subject to change without notice. Past performance is not indicative of future results.
SPi accepts no liability for any loss arising from the use of this report or its contents.