France Structured Products Issuance Reaches EUR 6.4Bn (+15.7% YoY) as Interest Rates Extend Their Lead Over Equity
Key Highlights
- Product Mix: Income leads YTD volume at 35.0%, ahead of Growth at 32.8% and Capital Protected at 32.3%, an evenly balanced three-way split that points to no single strategy commanding investor conviction.
- Asset Allocation: Interest Rates strengthened as the largest exposure, rising 43.1% to EUR 20.5Bn and 35.59% of YTD volume from 28.2% a year earlier, ahead of equity (indices) at 31.58% and equity (shares) at 21.14%, both lower than in 2025.
- Rates Exposure: Interest Rates accounted for 28.4% of August issuance, below 34.7% in July and 37.8% in August 2025, as rate-linked volume eased to EUR 1.8Bn from EUR 2.1Bn, indicating the monthly rotation has cooled even as the YTD position builds.
- Payoff Structures: Barrier digitals remain the most issued structure at 23.92%, followed by barrier phoenix at 22.36% and complex payoffs at 19.71%, with fixed income rates structures at 15.35%, confirming concentration in yield and rate-driven construction.
- Underlying Trends: Single underlying structures continue to dominate at 87.98% of YTD volume, with worst-of at 9.29% and baskets at 2.73%, while electrification led the themes among the most used decrement indices alongside transatlantic large cap exposure.
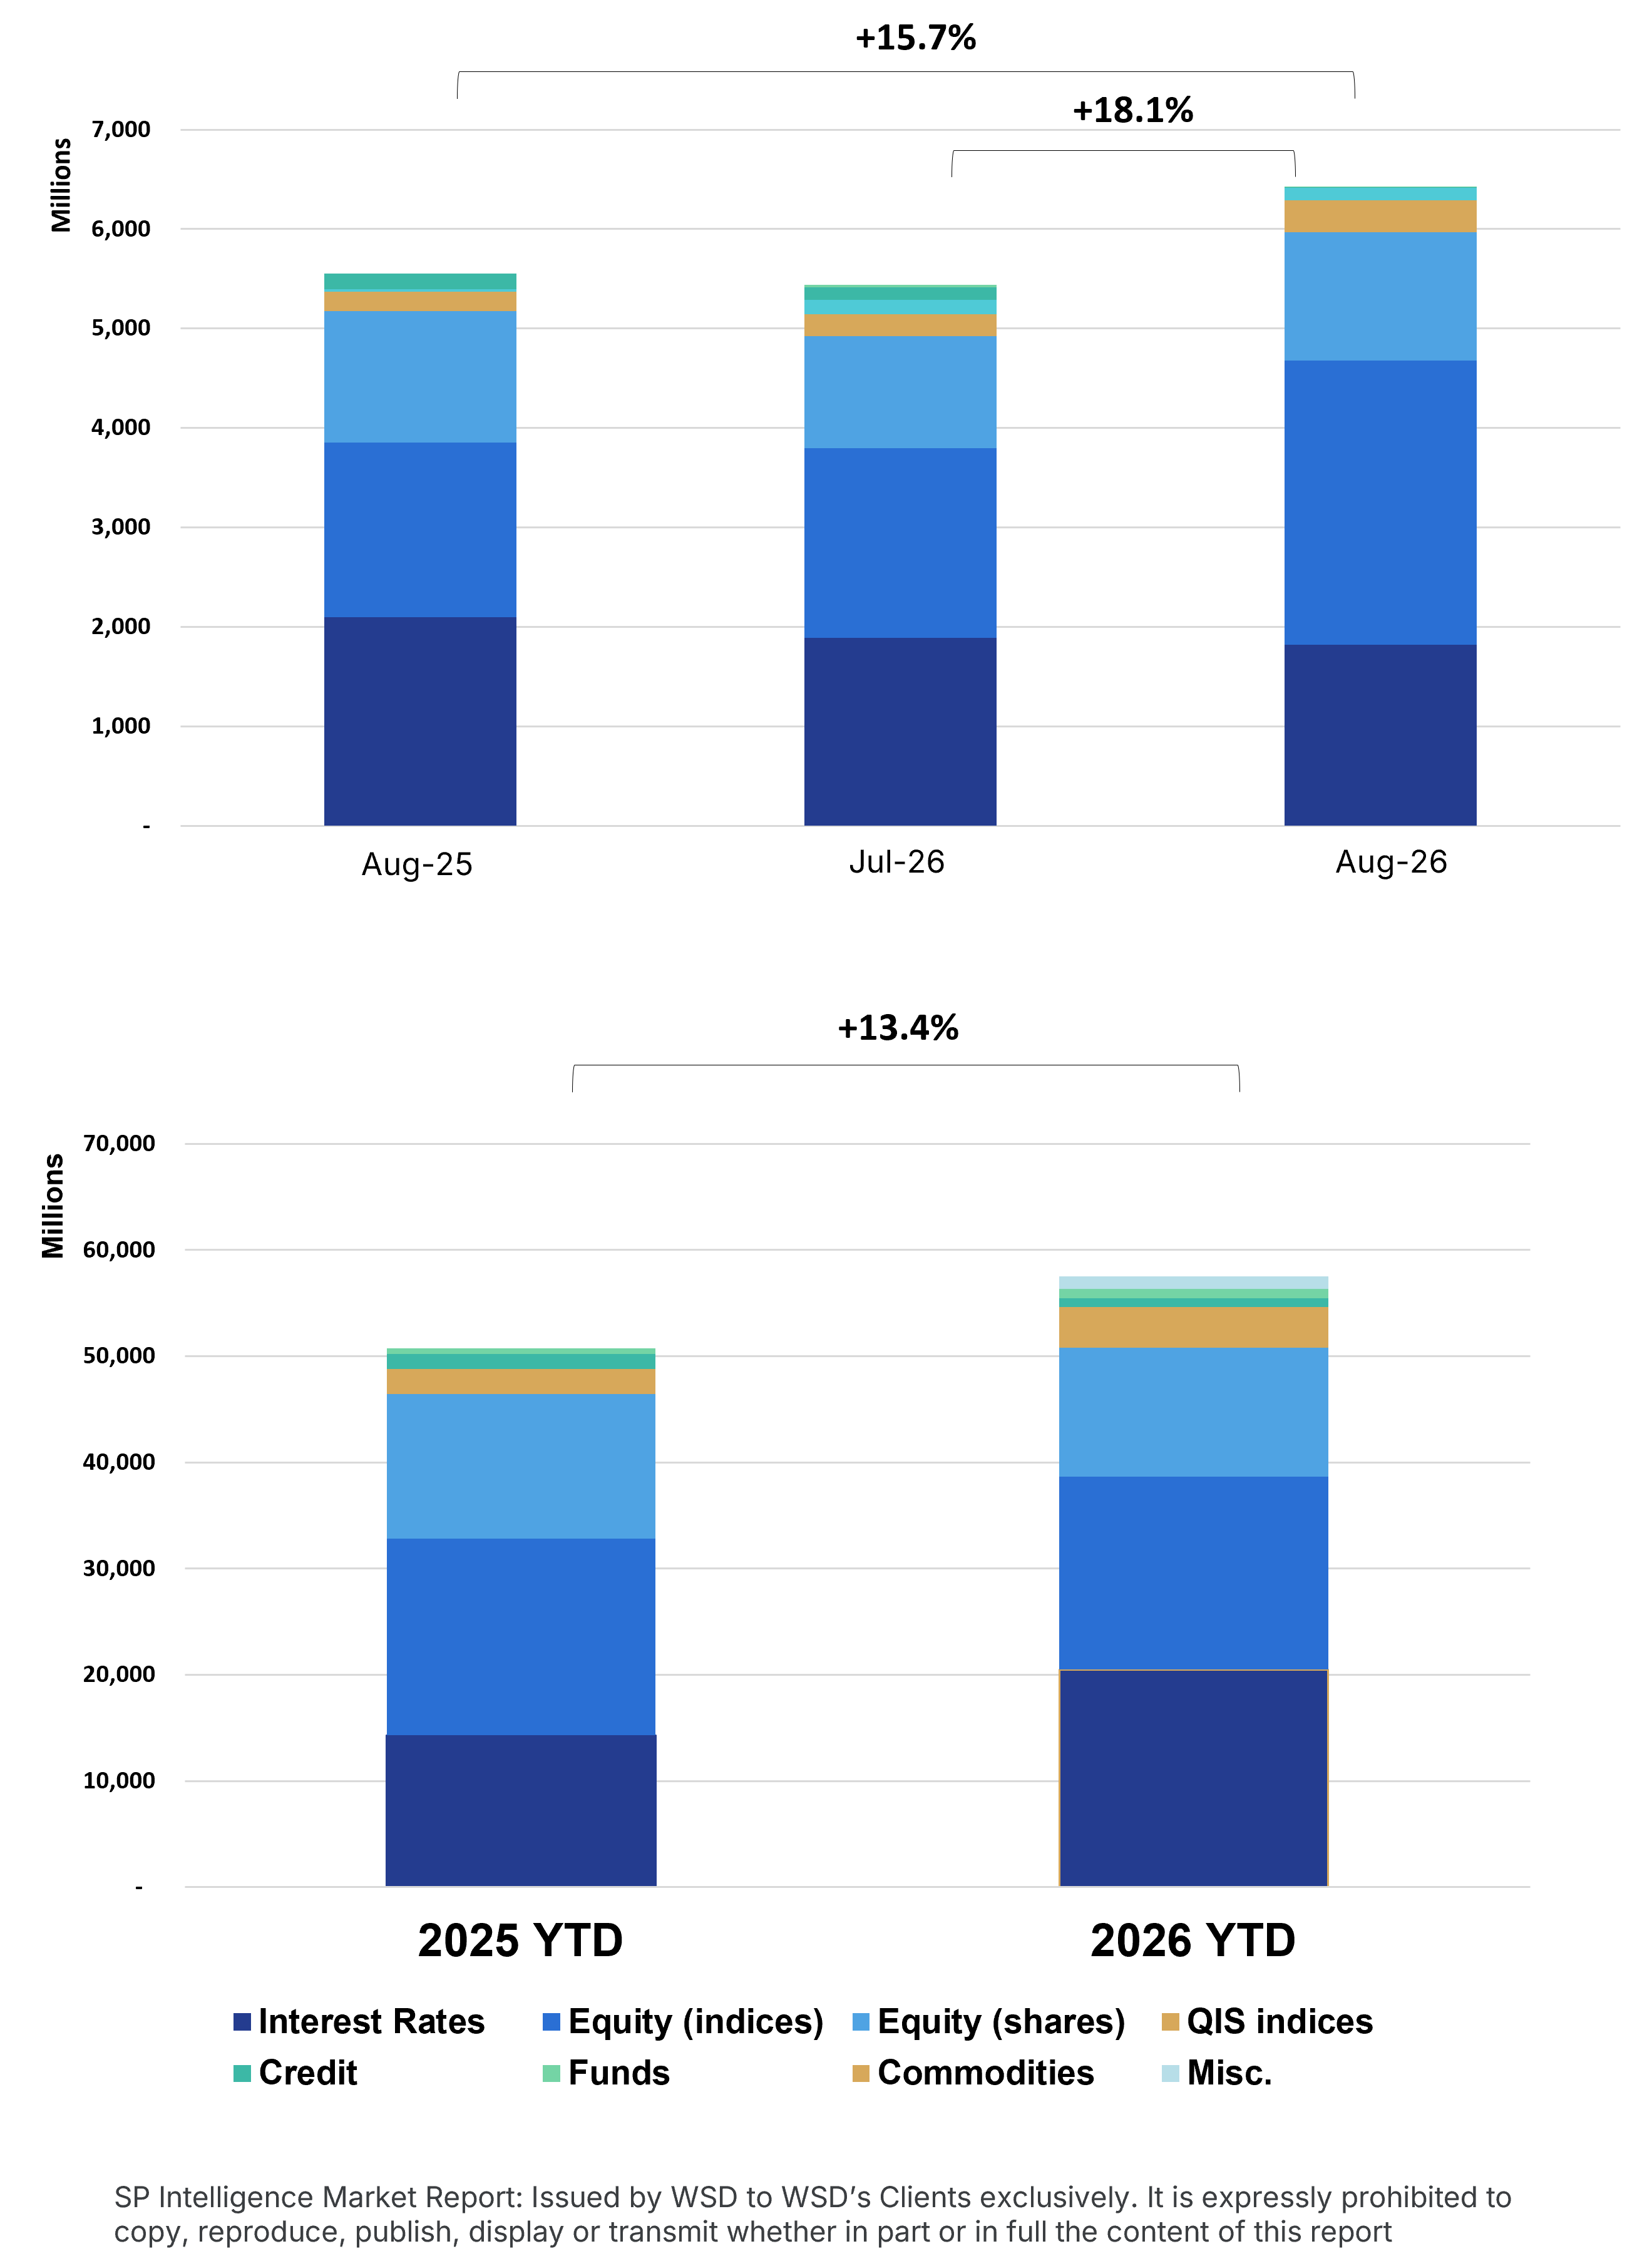
Market Overview
August 2026 confirms the continued build in rate-linked exposure that has defined the French market this year. Issuance reached EUR 6.4Bn, up 15.7% YoY and 18.1% on July, taking 2026 YTD volume to EUR 57.4Bn, an increase of 13.4% on the same period of 2025. The product mix remained evenly balanced across the three strategies, with Income taking the lead at 35.0% of YTD volume, ahead of Growth at 32.8% and Capital Protected at 32.3%. Structurally the market remains simple, with single underlying structures at 87.98% of YTD volume, worst-of at 9.29% and baskets at 2.73%. Payoff construction stays concentrated, with barrier digitals the most issued structure at 23.92%, followed by barrier phoenix at 22.36% and complex payoffs at 19.71%, while fixed income rates structures accounted for 15.35%. Interest Rates strengthened their position as the largest exposure, rising 43.1% to EUR 20.5Bn and 35.59% of YTD volume from 28.2% a year earlier, ahead of equity (indices) at 31.58% and equity (shares) at 21.14%, with QIS indices rising to 6.65% from 4.7%. Within August itself rates accounted for 28.4% of issuance, below 34.7% in July. Overall, August reflects a broad-based, rate-led market, combining firm issuance growth, an evenly balanced product mix, and continued dominance of single underlying, barrier-driven construction.
Methodology & Notes
This report is based on SPi's proprietary database of structured products distributed in France. Figures reflect best-effort estimates based on available market data at the time of publication.
Disclaimers
Data Disclaimer (Best Effort / Completeness)
The information presented in this report is based on data collected from a variety of public and proprietary sources. While reasonable care has been taken to ensure accuracy, the data may be incomplete, subject to revisions, or may not capture the entirety of the market. SPi makes no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information.
General Disclaimer
This document is provided for informational purposes only and does not constitute investment advice, an offer, or a recommendation to buy or sell any financial instrument or to adopt any investment strategy. The views expressed are those of SPi at the date of publication and are subject to change without notice. Past performance is not indicative of future results.
SPi accepts no liability for any loss arising from the use of this report or its contents.