France Structured Products Issuance Reaches EUR 5.43Bn (-13.7% YoY) as Equity Indices Retake the Monthly Lead Over Rates
Key Highlights
- Product Mix: Growth leads 2026 YTD issuance at 34.0%, narrowly ahead of Income at 33.9% and Capital Protected at 32.1%, an unusually even three-way balance indicating the rotation towards yield generation has stalled.
- Asset Allocation: Interest Rates remains the largest YTD category at 34.48%, up from 28.20%, extending its lead over Equity indices at 32.13%, down from 36.50%, with Equity shares at 21.51% and QIS rising to 6.76% from 4.70%.
- Monthly Reversal: Equity indices was July's largest asset class at EUR 2.4Bn, ahead of Interest Rates at EUR 1.54Bn as rate-linked volumes fell 33.6% MoM, with QIS at EUR 272Mn (5.0%) the only significant category growing both MoM and YoY.
- Structure Mix: Single underlying products account for 87.53% of YTD volumes, with worst-of structures easing to 9.64% and baskets at 2.83%, reinforcing a clear preference for simplified construction.
- Payoff Structures: Barrier Digital leads at 24.80%, with Complex structures moving into second at 21.02% ahead of Barrier Phoenix at 20.44%, the top four categories representing 80.7% of issuance and confirming concentration in structured yield and rate-driven solutions.
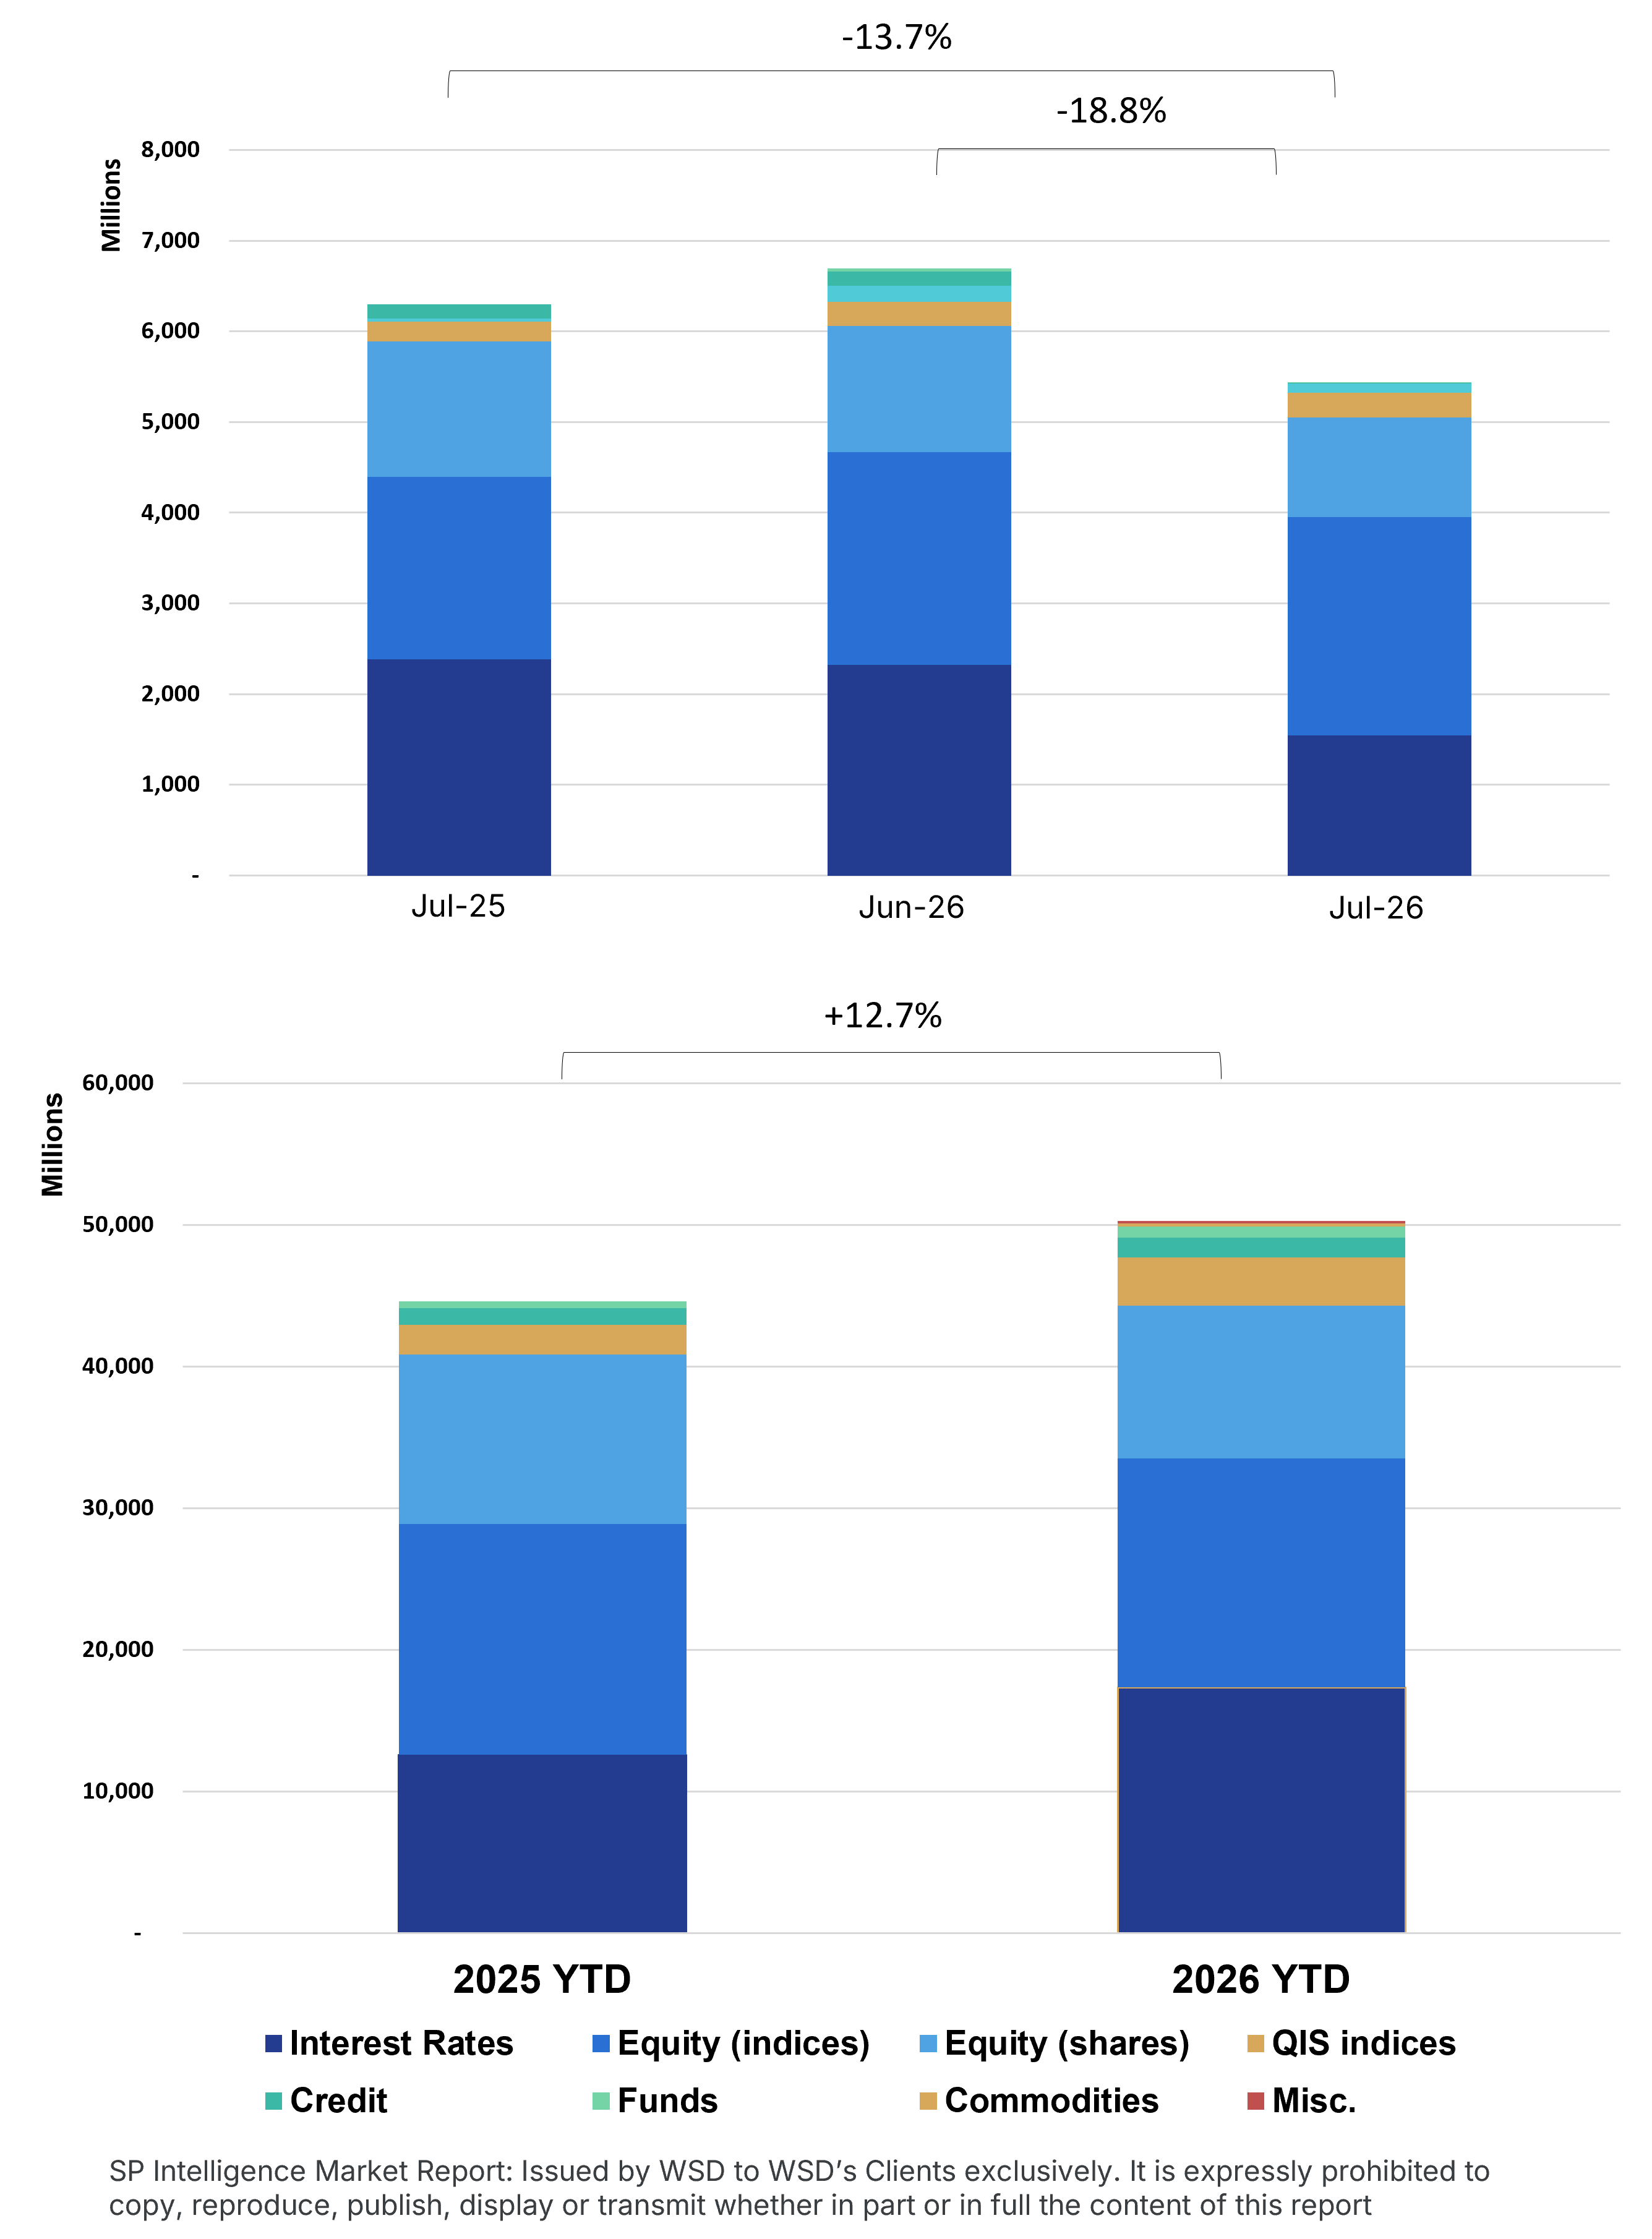
Market Overview
July 2026 reflects a pause in the rotation that has shaped the French market this year. Issuance reached EUR 5.43Bn, down 13.7% YoY and 18.8% on June's EUR 6.69Bn, taking 2026 YTD volumes to EUR 50.27Bn, a 12.7% increase YoY. Growth strategies now lead the YTD product mix at 34.0%, marginally ahead of Income at 33.9% and Capital Protected at 32.1%, reversing June's clear Income lead and leaving the three families within two percentage points of one another. Structurally the market remains simple: single underlying products account for 87.53% of YTD volumes, with worst-of structures easing to 9.64% and baskets marginal at 2.83%, while Notes represent 90.2% of issuance against 9.76% for Certificates. Payoff construction stays concentrated, with Barrier Digital the largest segment at 24.80%, Complex structures moving into second at 21.02% ahead of Barrier Phoenix at 20.44%, and fixed income and rates payoffs at 14.41%. Interest Rates leads the YTD asset allocation at 34.48%, up from 28.20%, ahead of Equity indices at 32.13%, though within July itself Equity indices was the largest asset class at EUR 2.4Bn against EUR 1.54Bn for rates. Overall, July reflects a market in balance rather than transition, combining softer monthly volumes, an unusually even product mix, and continued dominance of barrier-driven and rate-linked construction.
Methodology & Notes
This report is based on SPi's proprietary database of structured products distributed in France. Figures reflect best-effort estimates based on available market data at the time of publication.
Disclaimers
Data Disclaimer (Best Effort / Completeness)
The information presented in this report is based on data collected from a variety of public and proprietary sources. While reasonable care has been taken to ensure accuracy, the data may be incomplete, subject to revisions, or may not capture the entirety of the market. SPi makes no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information.
General Disclaimer
This document is provided for informational purposes only and does not constitute investment advice, an offer, or a recommendation to buy or sell any financial instrument or to adopt any investment strategy. The views expressed are those of SPi at the date of publication and are subject to change without notice. Past performance is not indicative of future results.
SPi accepts no liability for any loss arising from the use of this report or its contents.